
Cipher Digital shares slumped after the Bitcoin miner issued 40.7 million shares and borrowed $850 million to fund AI expansion.
Data from Yahoo Finance shows that the company’s stock closed at $8.98 on Oct. 16, down 10.6% for the session and at its lowest level since September 2025. The shares have lost more than 52% over the past year, reflecting mounting pressure on the company’s valuation as it pursues an expensive transition into high-performance computing infrastructure.
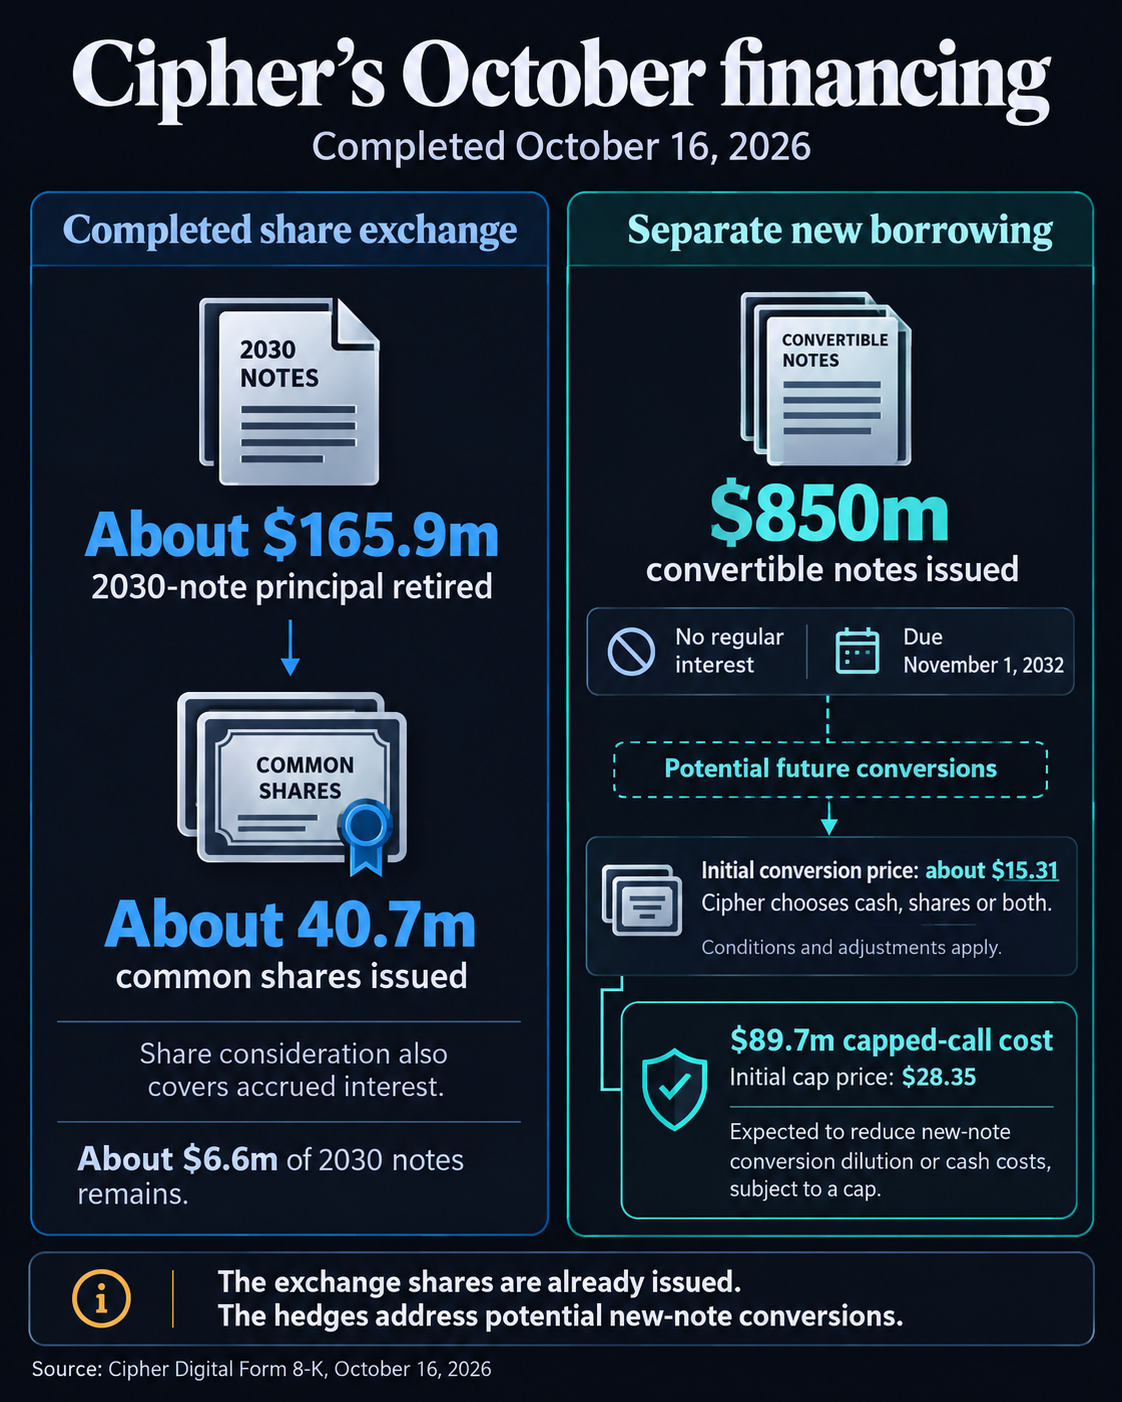
According to an Oct. 16 SEC filing, Cipher completed an exchange of approximately $165.9 million in convertible notes due 2030 for 40.7 million newly issued common shares, including consideration for accrued interest.
The transaction eliminates most of that debt series, leaving approximately $6.6 million outstanding, while immediately expanding the company’s share base and diluting existing investors.
The exchange comes amid a sharp selloff that has erased roughly 31% of Cipher’s market value per share since Oct. 12. Bondholders receiving the new shares could also create additional selling pressure if they liquidate their holdings or unwind hedging positions tied to the original debt.
Meanwhile, Cipher completed a separate $850 million convertible bond offering on Oct. 16, increasing its borrowing commitments as it accelerates investment in data centers designed to support artificial intelligence workloads.
The transactions leave Cipher with about $684 million more in outstanding debt principal from these two deals, along with immediate shareholder dilution, increasing the importance of its ability to generate returns from its expanding infrastructure portfolio.
AI expansion adds pressure to Cipher’s balance sheet
The new convertible notes mature in November 2032 and carry no regular interest payments, allowing Cipher to fund development without an immediate increase in coupon expenses.
However, investors holding the notes can demand cash repayment in November 2030 under specified conditions, potentially creating a substantial refinancing obligation before their scheduled maturity.
The securities also carry an initial conversion price of approximately $15.31 per share, substantially above Cipher’s latest closing price. The company spent approximately $89.7 million on capped-call transactions intended to limit potential dilution from future conversions, with protection extending to an initial share price of $28.35.
Cipher expects approximately $835.1 million in proceeds after initial purchaser discounts and commissions, before offering expenses. After the capped-call costs, the remaining funds will support additional investment in Barber Lake, other high-performance computing developments and new sites.
The spending comes as Cipher seeks to replace its dependence on Bitcoin mining with recurring revenue from leasing infrastructure to major computing customers.
In its August business update, the company reported about $25 million in second-quarter revenue and a $30 million adjusted EBITDA loss, underscoring the gap between its current operating income and the capital needed for expansion.
However, Cipher also began delivering capacity at its Black Pearl data center in August, two months ahead of schedule, triggering initial rental payments from its hyperscale tenant.
That development provides an early commercial foundation for its AI strategy, although growing financing commitments increase pressure to complete additional projects and convert contracted capacity into cash flow.
The company is also advancing construction at Barber Lake and Stingray while expanding its development pipeline. With the latest convertible offering complete, investors will watch whether new rental income can support those commitments before holders gain the right to demand cash repayment in 2030.
